Loading...


A network token is similar to an acquirer token in that it reduces PCI DSS scope and improves security by swapping sensitive card data (PAN) for non-sensitive data. However, network tokens are generated by the card brands such as Visa and Mastercard. Each brand maintains its own secure repository of network tokens that serve as payment credentials. So, if a customer loses their card or it’s stolen, the brand updates their token automatically without any disruption in service.
With network tokens, merchants can:
We work with the card brands to provide a Card Storage service to merchants who want to initiate transactions using network tokens. This also includes generating cryptograms, which are required for transactions that are customer initiated.
In this section, we present some “real world” examples that can be enabled through our Network Tokens - Card Storage service. Keep in mind that this section doesn’t cover all of the use cases.
A merchant who was previously with another payment gateway provider wants to migrate all repeat payments, such as subscriptions, to our gateway. The merchant can just provide the Funding Primary Account Numbers (FPANs). We then convert the FPANs to network tokens on the merchant's behalf. Using network tokens results in higher acceptance rates and reduced involuntary drop-offs from continued repeat payments.
A merchant using an account updater to keep their customers’ cards up to date wants to reduce this burden as well as improve customer service. Since network tokens are managed by the card brands (like Visa or Mastercard), token updating is done automatically by them on behalf of the merchant. This results in higher acceptance rates because it reduces declined charges due to outdated credentials. Also, if a customer loses their card or it gets stolen, the card network updates the token directly so it continues to work without any service interruption, improving customer satisfaction.
A merchant wants to use multiple gateways for fallback or redundancy purposes. This way, if one of the gateways is slow or has an outage, another provider can be used so that there’s no interruption of payment processing. Since network tokens are fully portable (unlike acquirer tokens), the merchant can use them to switch between multiple providers as needed. This can also result in greater protection of customer PCI data.
A merchant wants to reduce the fees they have to pay for payment processing. To help with this, the merchant decides to use network tokens because they are cheaper to operate at volume with lower interchange fees compared to standard FPANs or tokens.
This section provides a high-level understanding of how the network tokenization process works for both customer-initiated transactions (CITs) and merchant-initiated transactions (MITs).
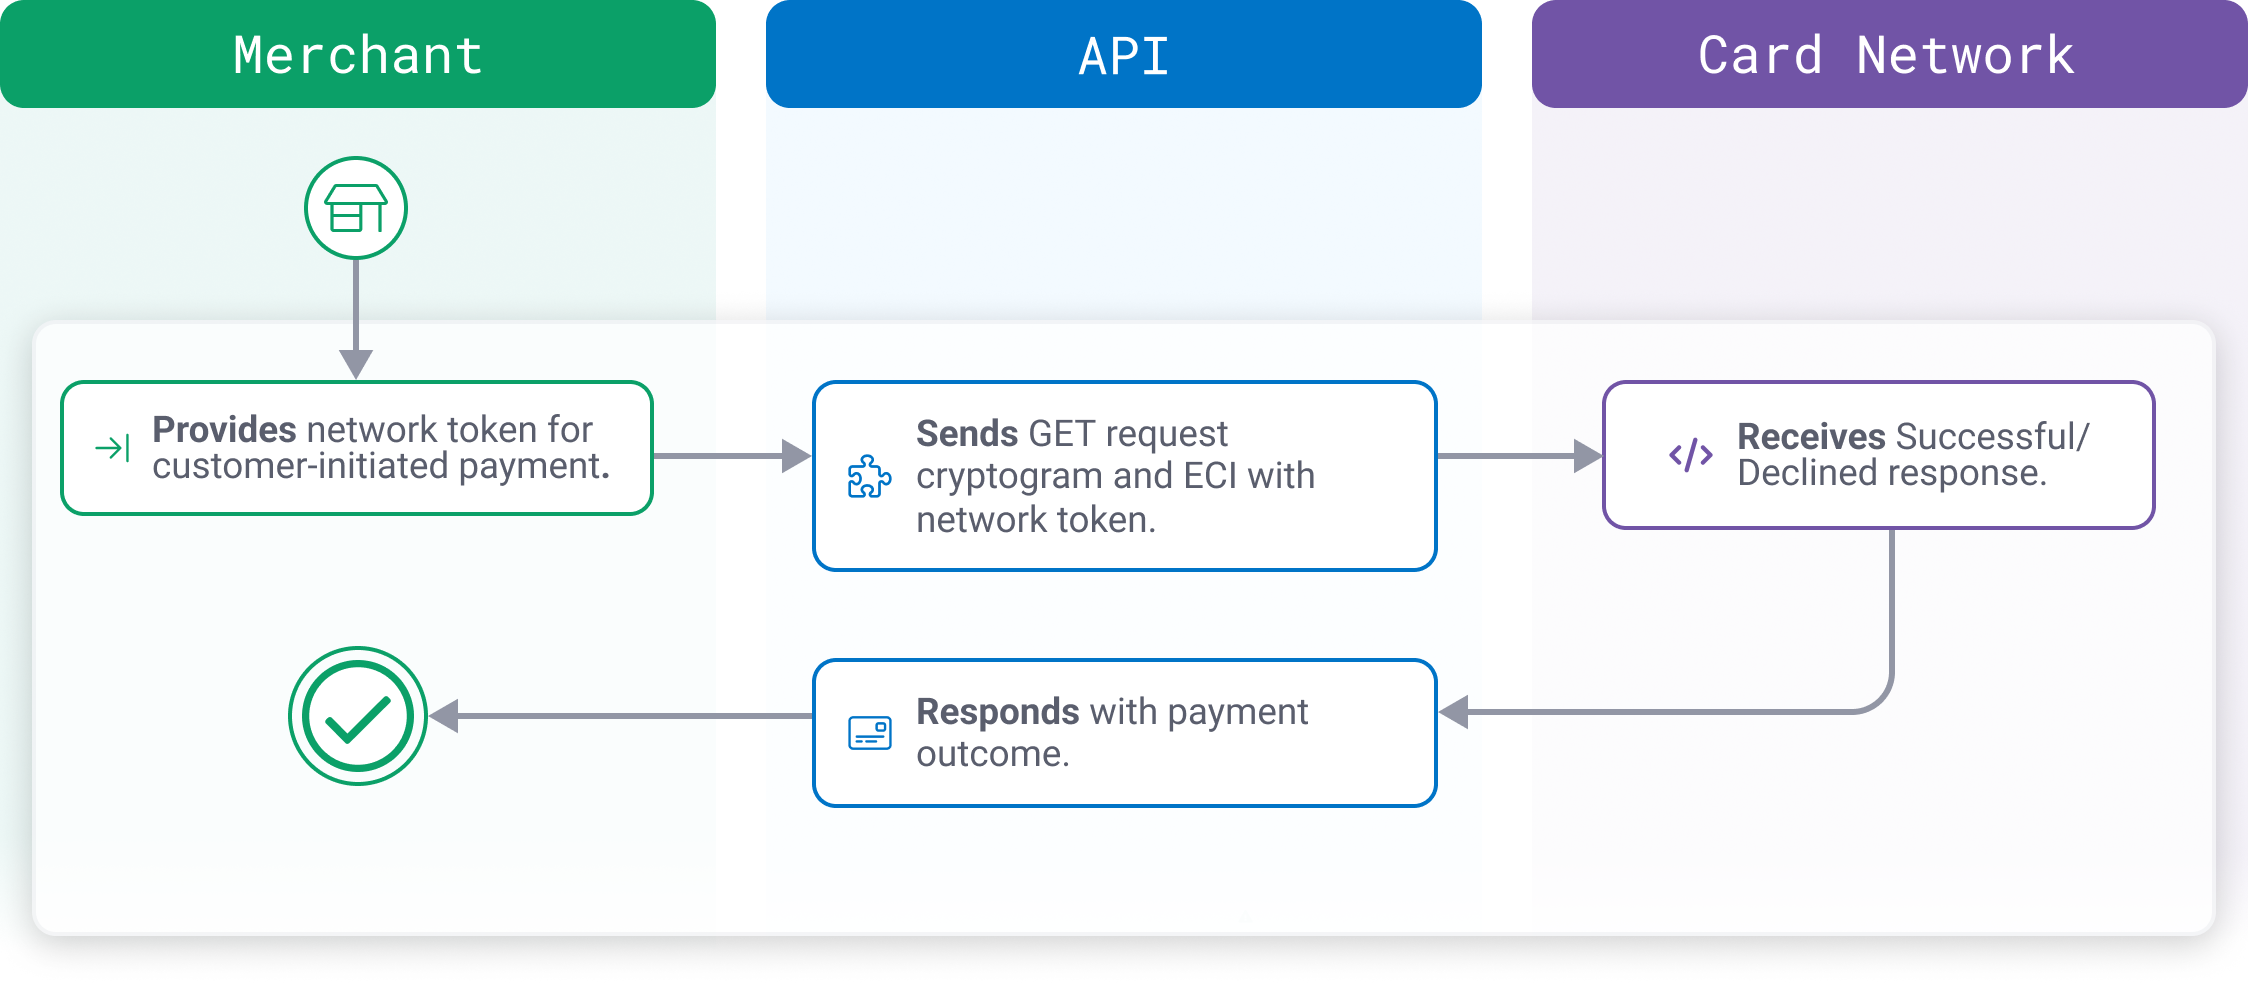
The following diagrams show the typical flow for requesting a cryptogram with an existing network token for a CIT.
Generate a cryptogram with existing network token
Make a payment with a network token
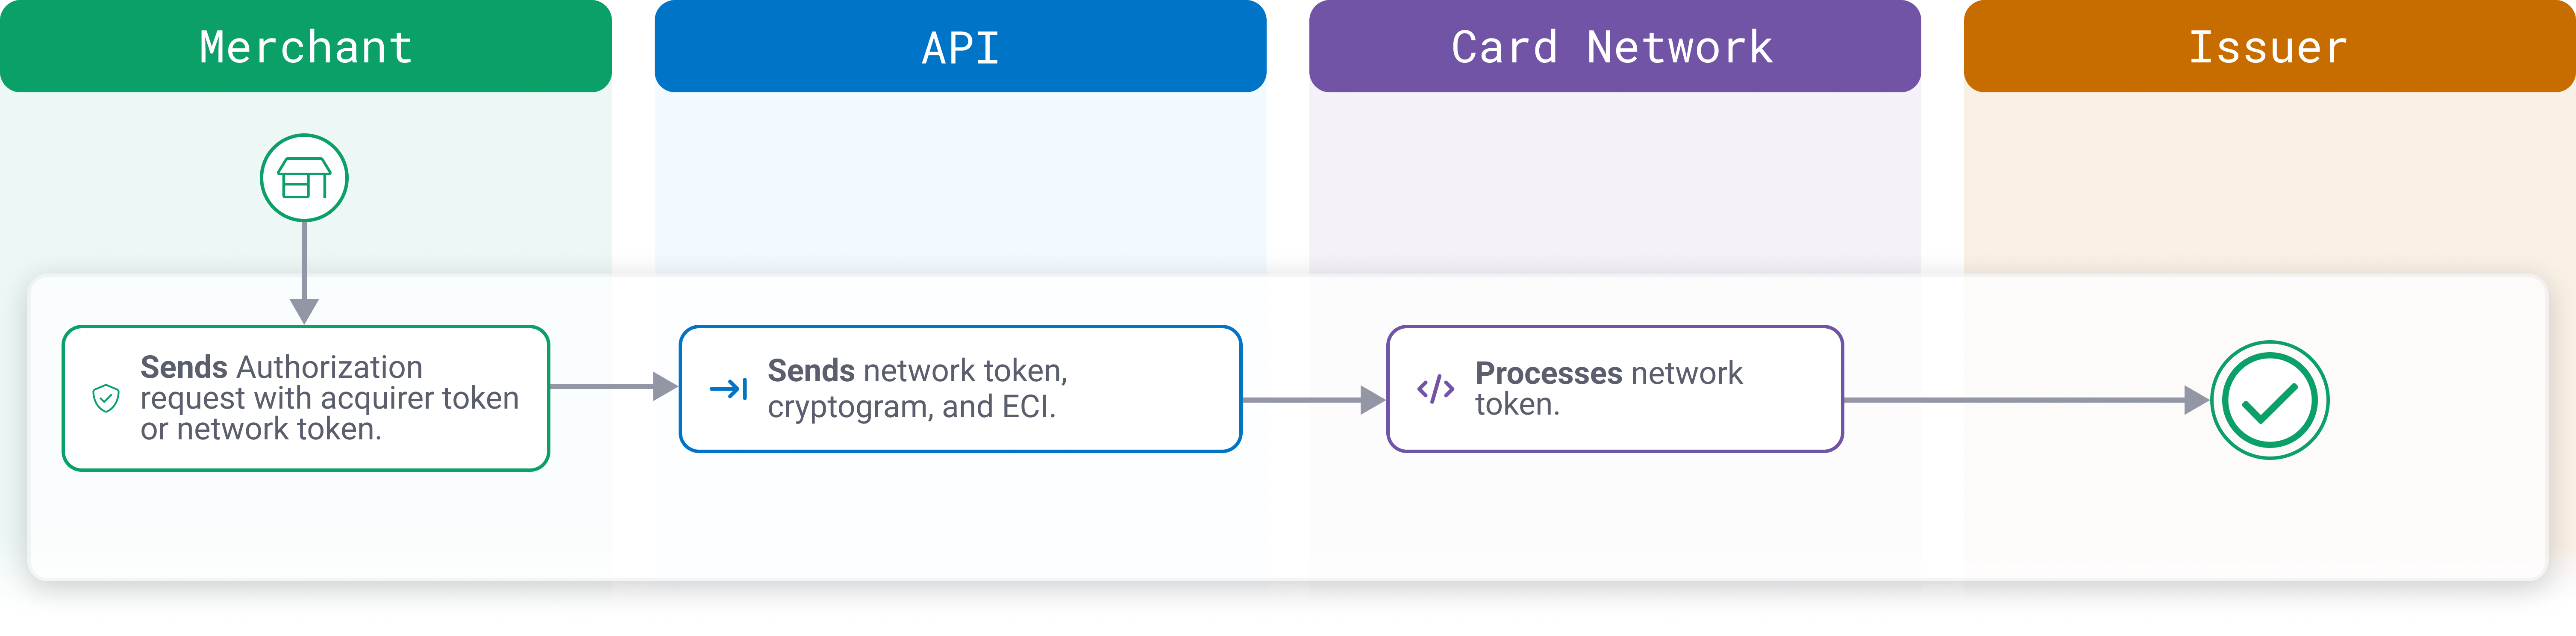
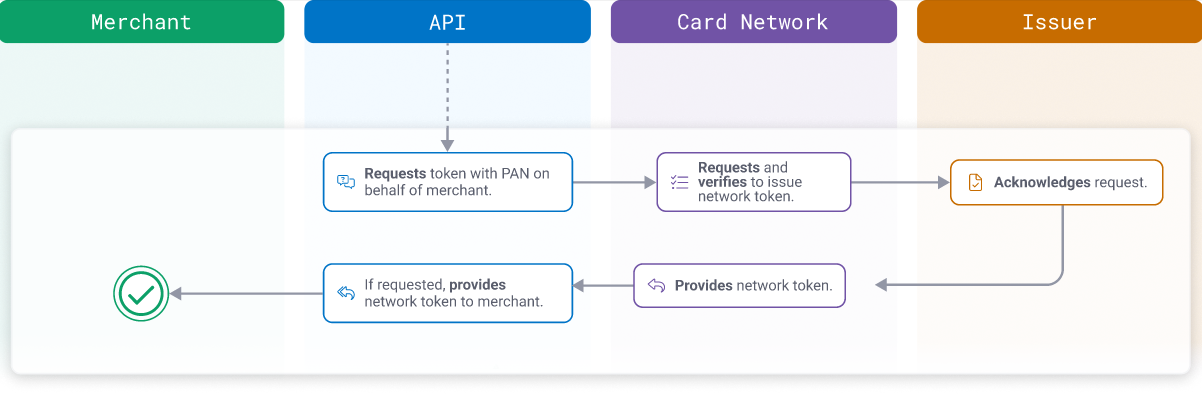
The following diagrams show the typical flow for generating a network token for an MIT.
Create a network token
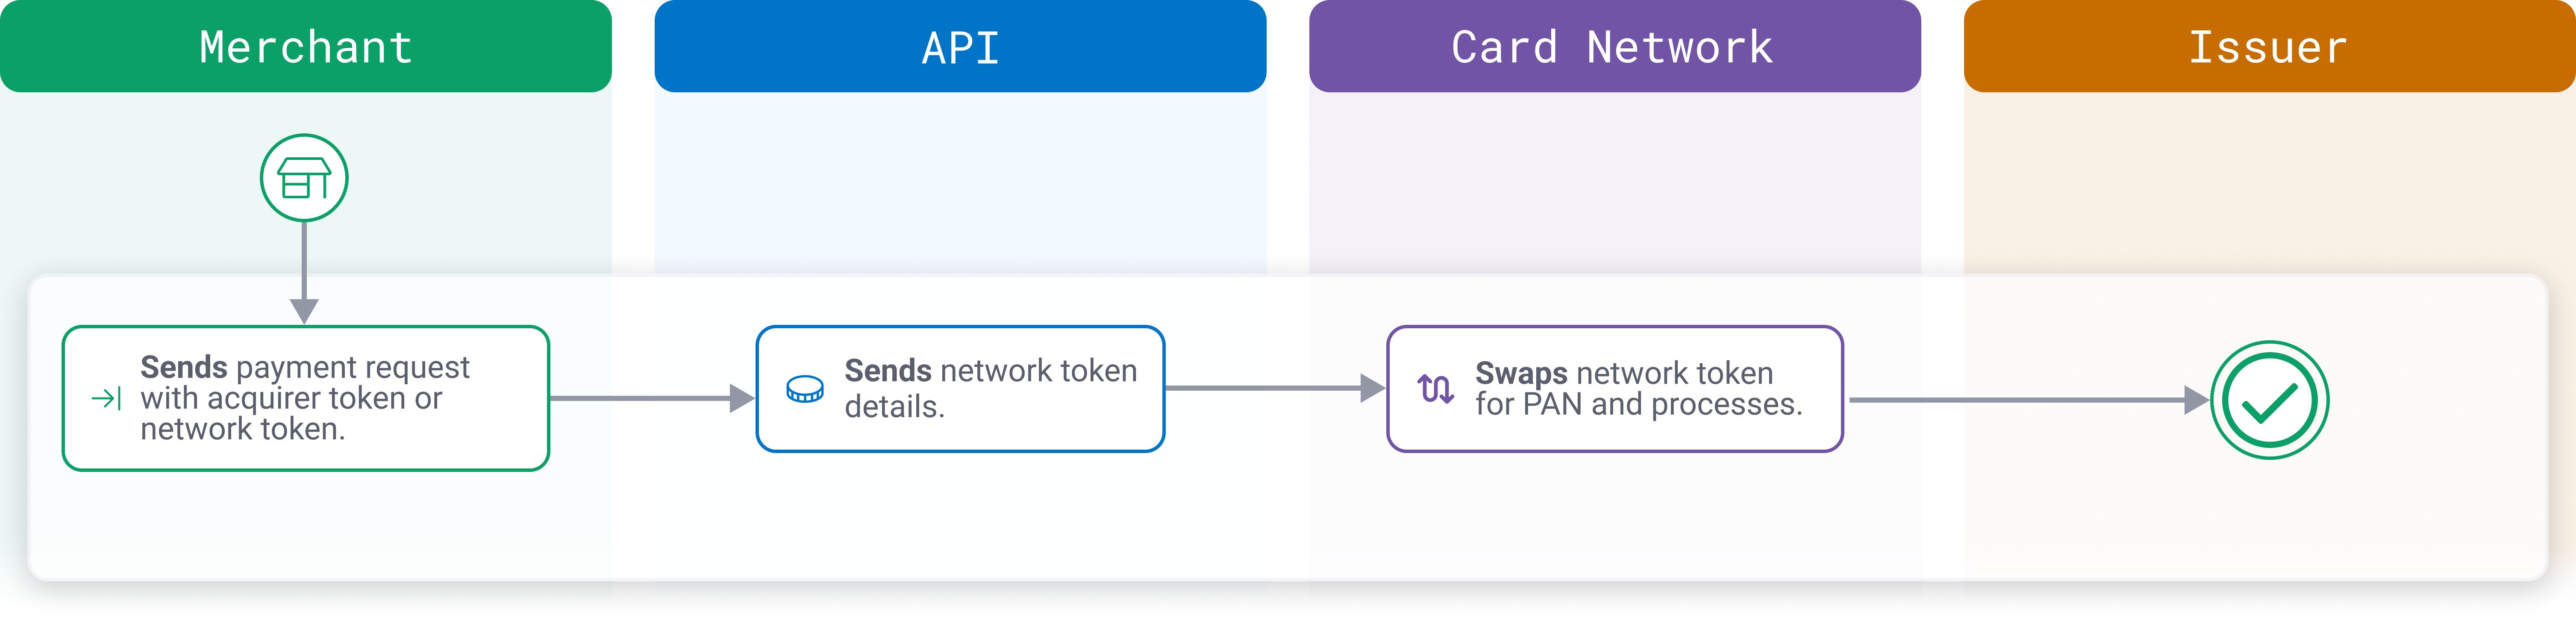
Make a payment with a network token
To get started with network tokens, see our guide.
Remember to first register for a developer account if you don't already have one. Once logged in, you can request Sandbox credentials from your account.